-

EY’s 401(k) Match Is 25% of the First 6% for New Hires and 50% After Four Years
Ernst & Young’s 401(k) matches 25% of the first 6% of pay and 50% after four years, a 3% ceiling. Plan costs, the fund menu and the 33% match ratio.
-
The 10% 401(k) Penalty Is Not That Bad: Not Saving Is Much Worse
The 10% penalty is only on the money you take out, not your whole account. We ran 20 cases over 5 to 30 years. With a company match, the 401(k) wins every time.
-
C.H. Robinson’s 401(k) Pays Dollar for Dollar on the First 6%, While AI Reshapes the Payroll Behind It
C.H. Robinson matches 100% of the first 6% of pay with no dollar cap, and a 69.19% observed match rate shows participants here defer well past the match line.
-
HP Inc. 401(k) Plan Review: 100% Match on First 4%, Roth 401(k), and What the Layoffs Mean for Your Retirement
HP matches 100% of the first 4% you contribute, dollar-for-dollar. With 6,000 job cuts planned, here is what HP employees should know about their 401(k).
-

Never Too Late to Start Saving, A 53-Year-Old Man’s Story
Markets moved higher last week as momentum stocks continued to lead. Trump Accounts launched for children, nearly half of young adults live with parents, and a 53-year-old asks if its too late to retire. Plus: Roth conversion tax traps, RMD surprises, and three calculators to try.
-
Trump Account: A Children’s IRA Worth Understanding
The government is about to give newborns $1,000. The Trump Account, officially a 530A account, launched July 4, 2026. Here’s how it works, how it compares to a 529, and what the compounding numbers actually look like.
-
The Cargill Partnership Plan Review: Safe Harbor Match, ESOP Structure, and What 8,000 Layoffs Mean for Your 401(k)
The Cargill Partnership Plan offers a safe harbor match of 100% on the first 3% of pay and 50% on the next 2%, with contributions going into the Cargill ESOP Stock Fund. With $8.9 billion in assets and 46,000 participants, it is a strong plan that deserves attention amid the company’s restructuring.
-
Cisco 401(k) Plan Review: 50% Match, Record Revenue, and 4,000 Job Cuts for AI Pivot
Cisco’s 401(k) offers a 50% match up to 6% of salary with 3-year vesting and $22.7B in BlackRock institutional funds. Record revenue and 4,000 AI layoffs reshape the picture.
-
Macy’s 401(k) Review: 58% Match Rate, Tiered Structure, and a Lean Fund Lineup
Macy’s 401(k) offers a 58.3% match rate (100% on first 1% + 50% on next 5%), 2-year vesting, and Roth 401(k). But the 7-fund lineup is one of the leanest in retail. Here’s what employees should know.
-
Target’s 401(k) Review: 100% Match on 5% with Immediate Vesting
Target matches 100% of employee contributions up to 5% of pay, with immediate vesting across 475,573 participants. The $14.4B plan offers 18 State Street ins…
-
Nike’s 401(k) Match Is Dollar-for-Dollar, Even When the Swoosh Is Struggling
Nike matches 100% of your first 5% contribution, putting up to $4,000 a year in free money for an $80K salary. With 17 BlackRock institutional funds and immediate vesting, the plan is solid.
-
General Dynamics 401(k) Review: 100% Match Up to 6% With $325 Million in Employer Contributions
General Dynamics matches 100% of the first 6% of compensation, contributing $325.5M annually for 46,065 participants with Roth 401(k) options available.
-
Walmart 401(k) Plan Review: 100% Match on 6% for 1.9 Million Employees
An hourly associate earning $30,000 a year would need to contribute 6%, or $1,800 annually, to get the full $1,800 employer match. For a Walmart associate…
-
FedEx Office 401(k) Review: An 8% Employer Match With Immediate Vesting
Fedex will contribute 8% of your pay, which is $4,000. A 6% contribution equals $4,500 per year.
-
Caterpillar 401(k) Savings Plan Review: A 100% Match on 6% and $487 Million in Employer Contributions
The plan’s 2024 public filing disclosures shows employer contributions of $487 million against participant contributions of $456 million. That is a 106.9 percent…
-

Variable Annuity vs 401(k) vs IRA: A Beginner’s Guide
Variable annuities are rarely a substitute for 401(k)s and IRAs. This guide breaks down fees, tax treatment, and when a plain vanilla variable annuity like Vanguard’s might make sense—plus why a taxable brokerage account often wins anyway.
-

Your IRA Can Buy ETFs That Rival Even the Lowest-Cost Plan Funds
You could almost find the lowest cost reputable ETFs that rival against those lowest funds offered in some large retirement plans.
-

Understand Mega Backdoor Roth Conversion
- Latest in Retirement Savings & Personal Finance
- Understand Mega Backdoor Roth Conversion
- Tools & Tips: Backdoor Roth IRA Pro-Rata Conversion Calculator
- Market Overview
-

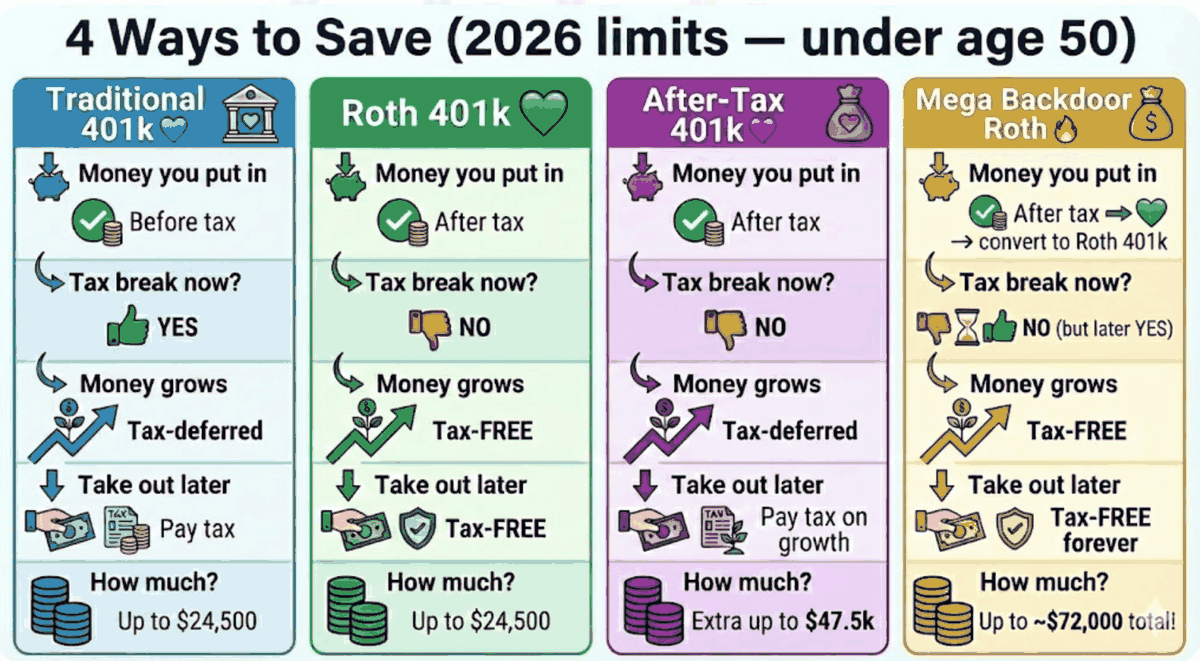
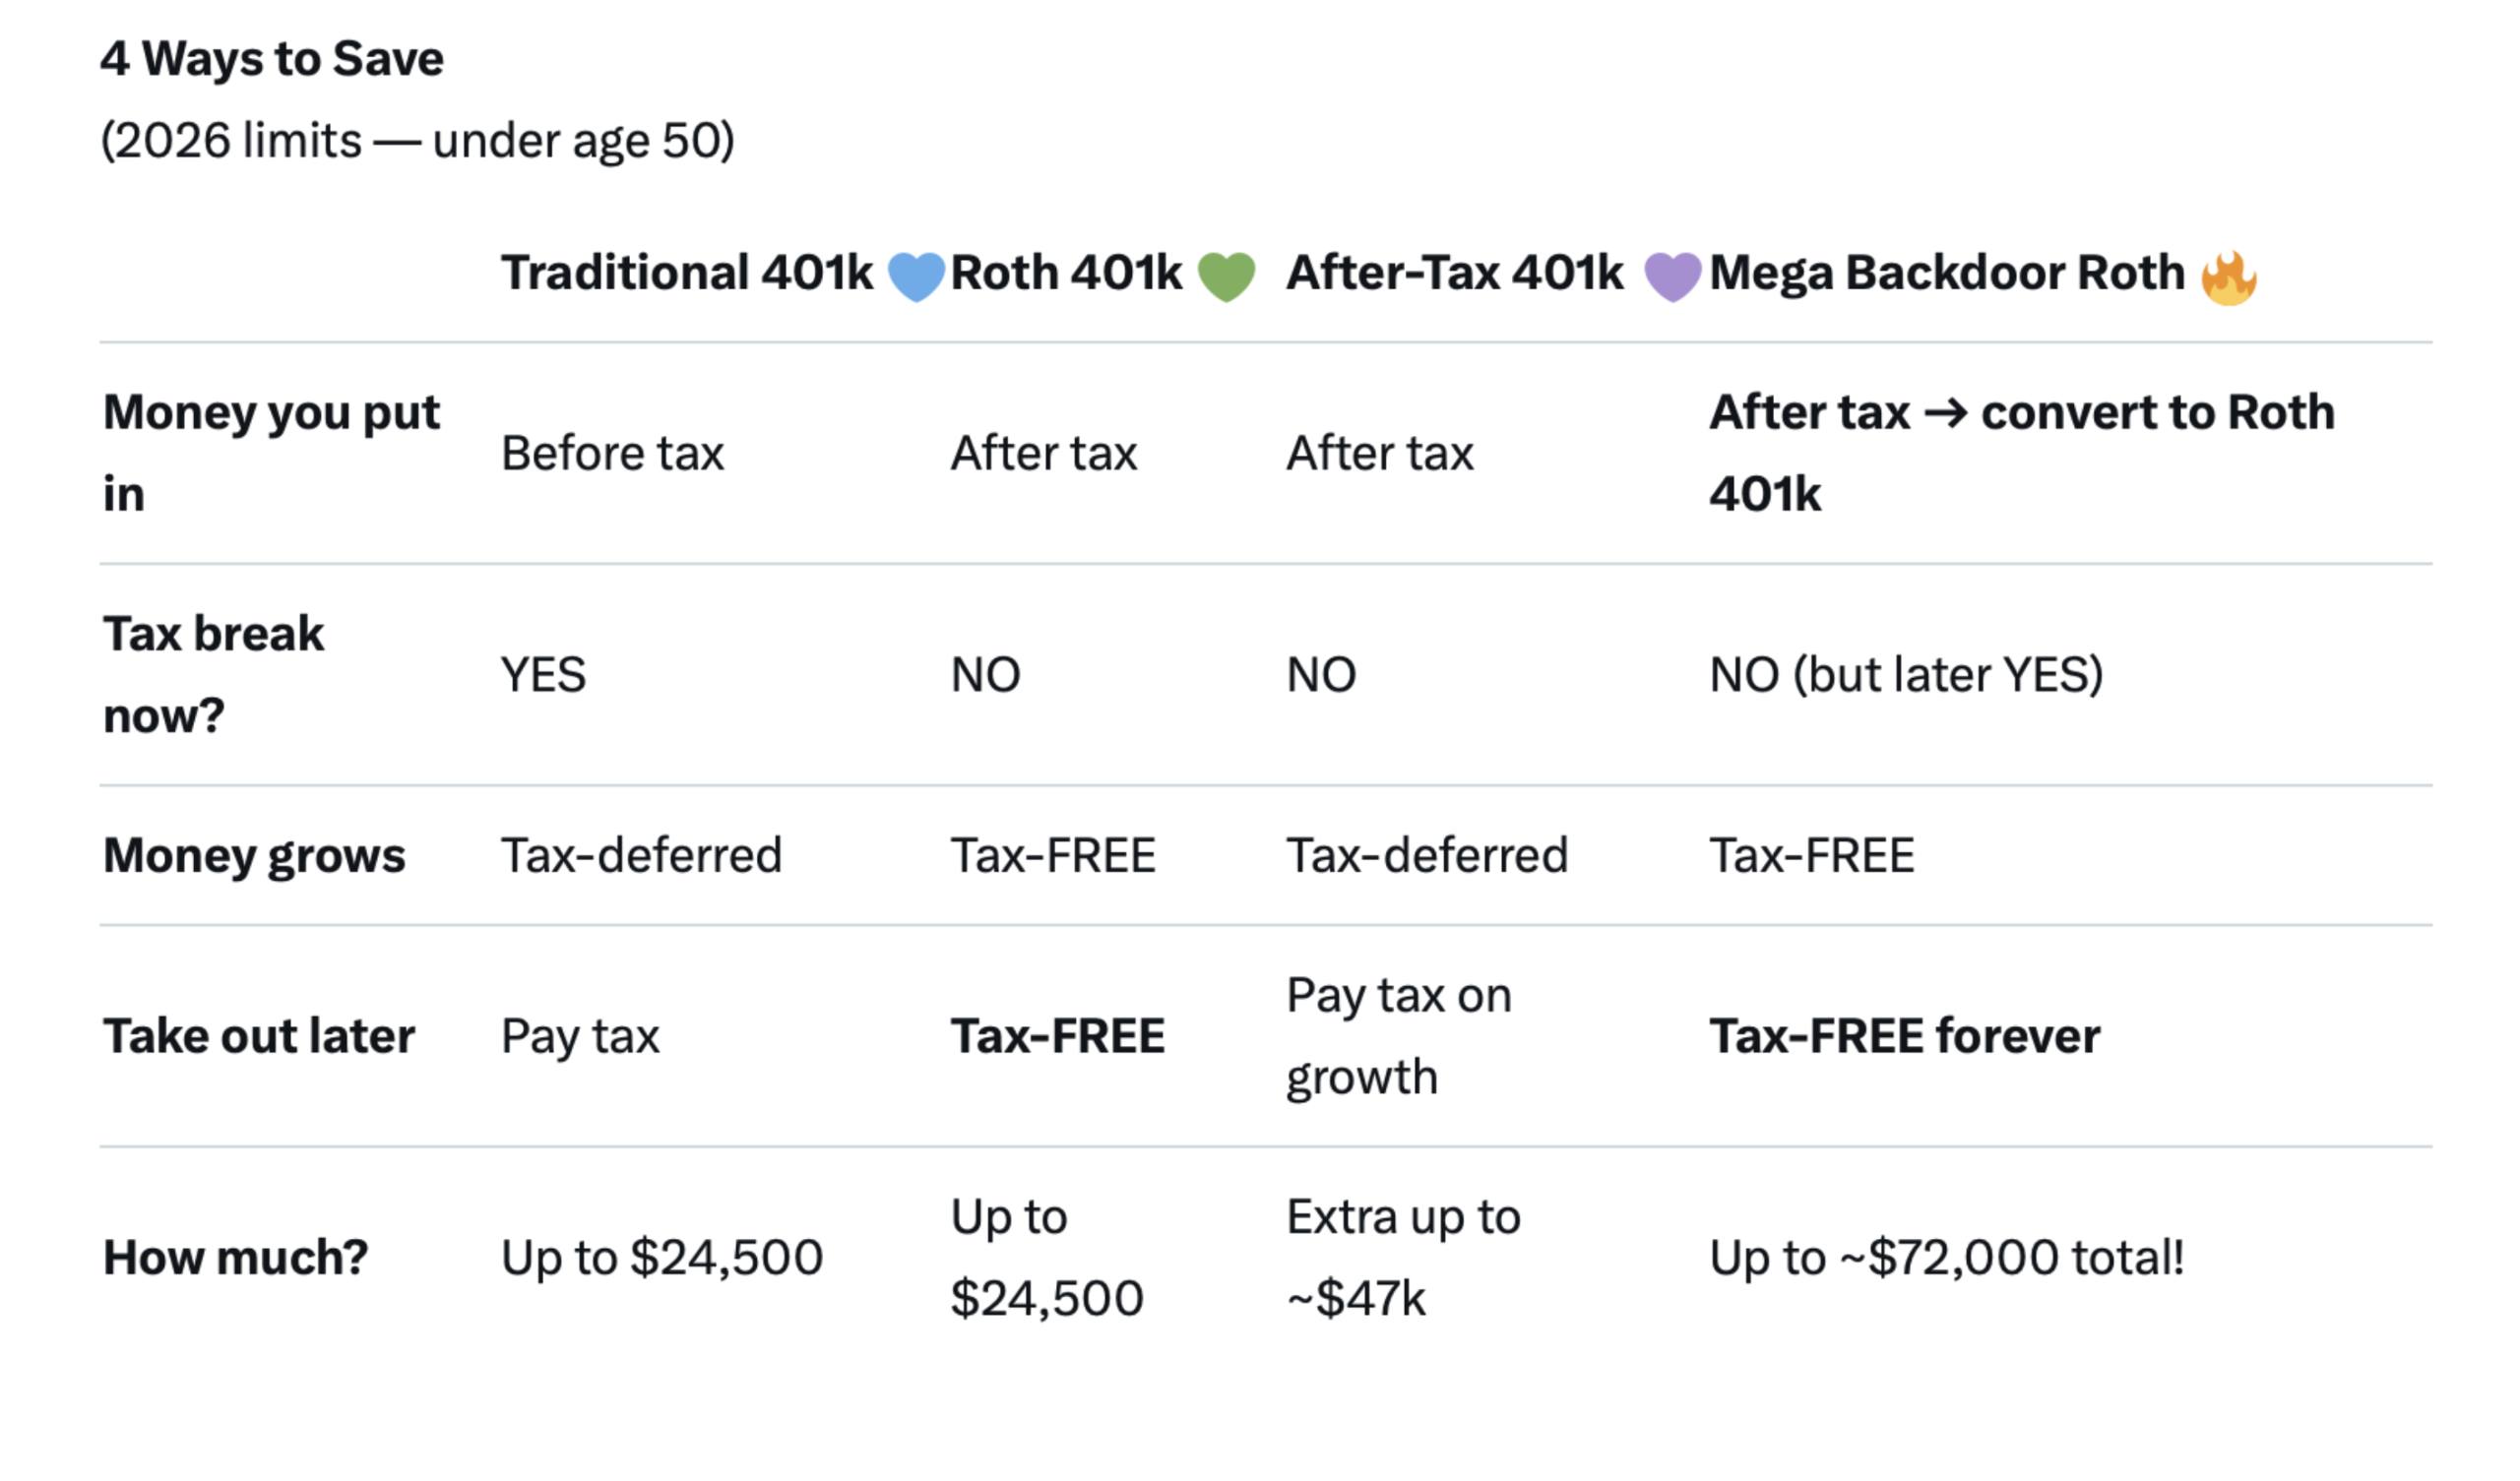
Mega Backdoor Roth Infographic
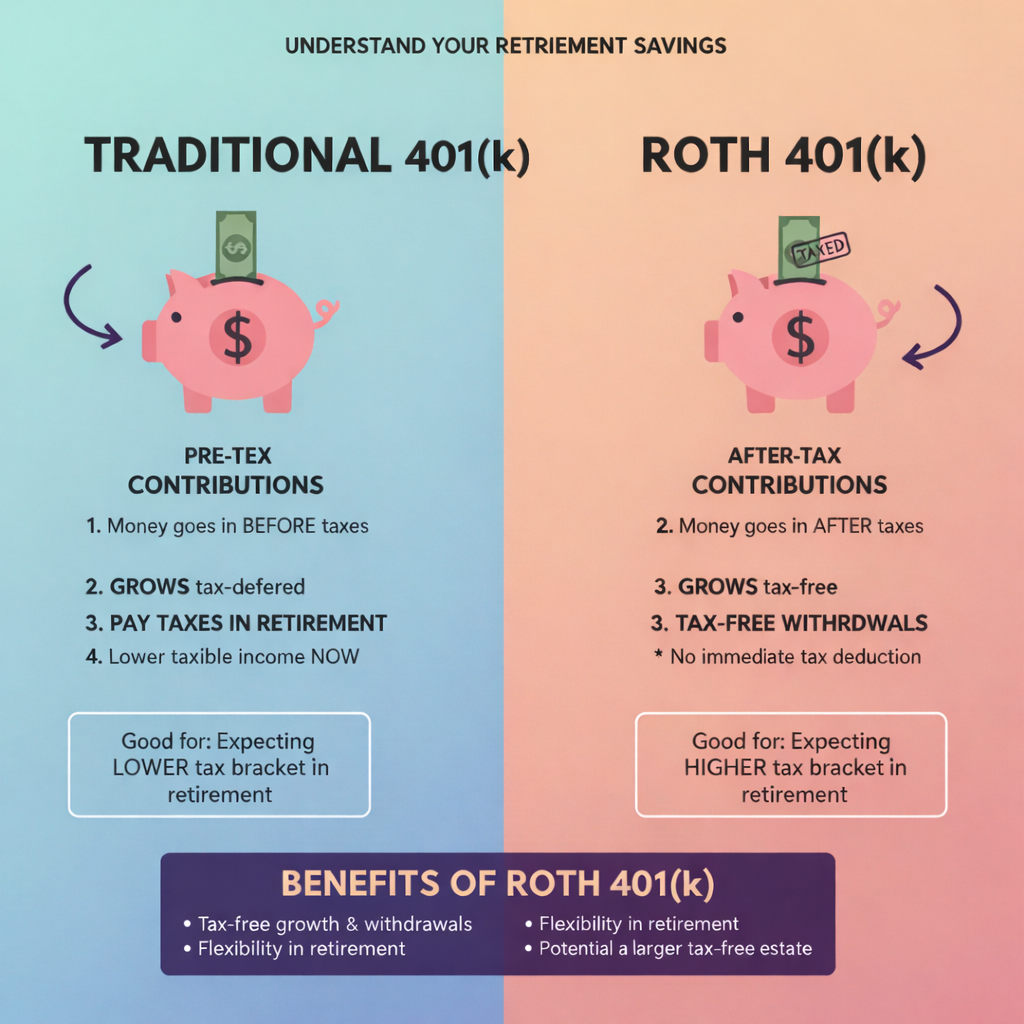
The infographic to illustrate the differences among traditional 401k, Roth 401k, After Tax 401k and Mega Backdoor Roth Conversion.
-

IRS Is Giving Out Money
- Latest in Retirement Savings & Personal Finance
- IRS Is Giving Out Money
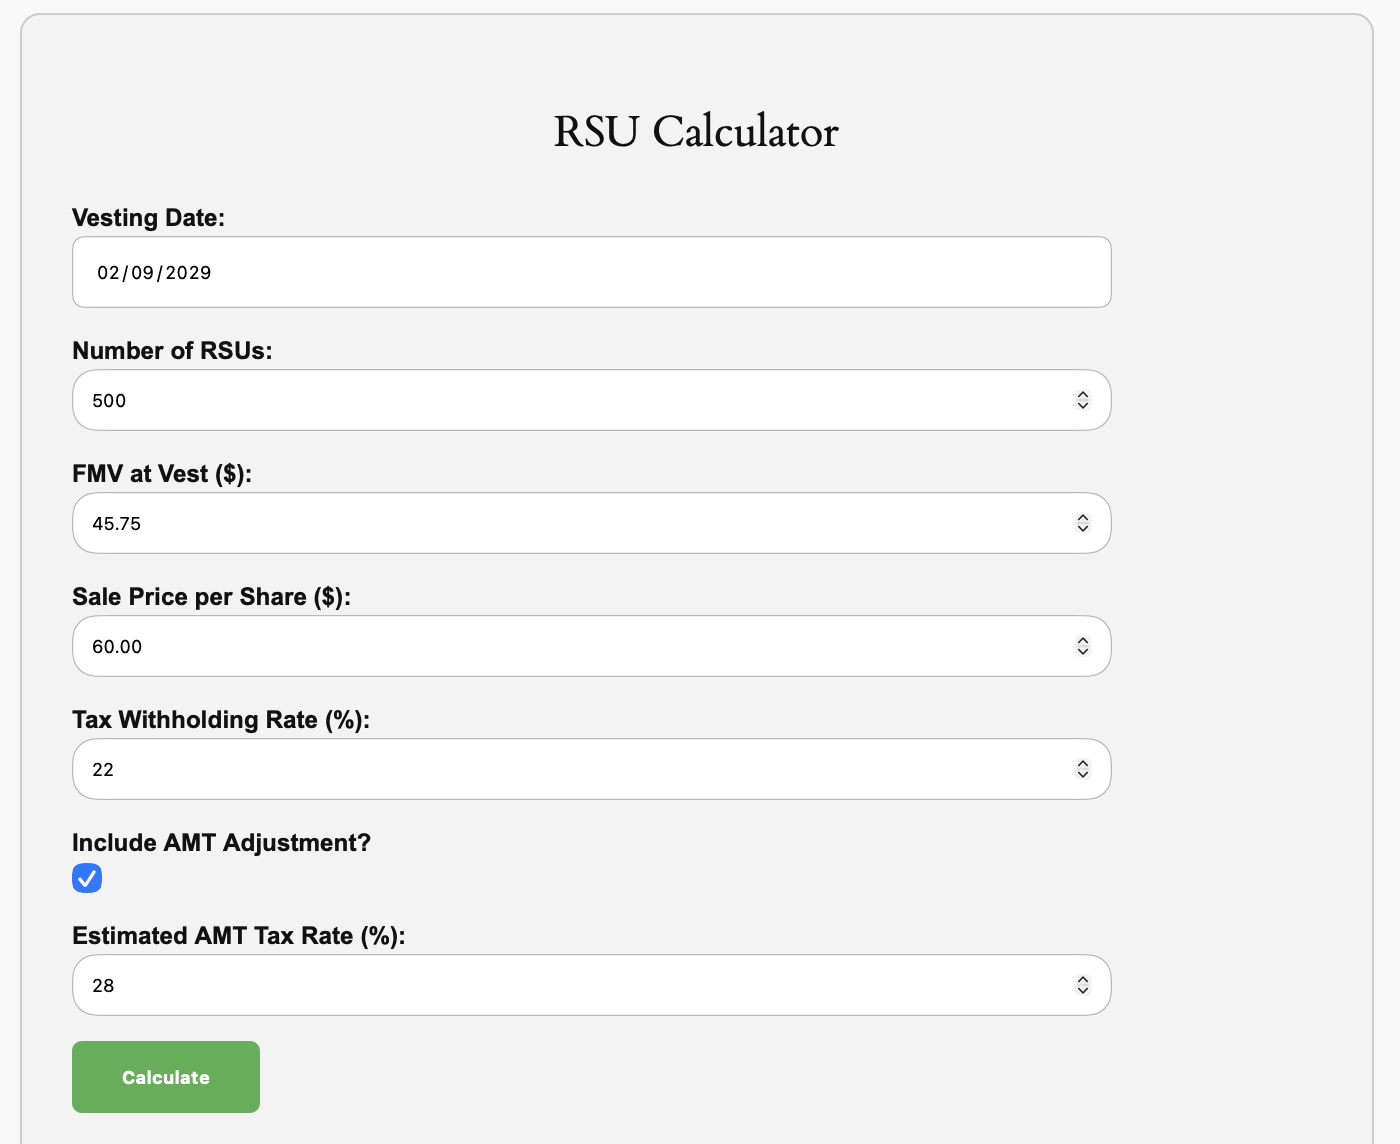
- Tools & Tips: RSU (Restricted Stock Unit) Calculator
- Market Overview
-

The Federal Reserve Bank and Your Money
- Latest in Retirement Savings & Personal Finance
- The Federal Reserve Bank and Your Money
- Tools & Tips: 401(k) Investment Assistant
- Market Overview
-

2026 Tax Season Begins Today
- Latest in Retirement Savings & Personal Finance
- 2026 Tax Season Begins Today
- Tools & Tips: Traditional 401(K) vs. Roth 401(K)
- Market Overview
-

Useful Tips for 401(k)s, IRAs, and RMDs in the New Year
- Latest in Retirement Savings & Personal Finance
- Useful Tips for 401(k)s, IRAs, and RMDs in the New Year
- Tools & Tips: Roth IRA Compounding
- Market Overview
-

The $7,000 Roth IRA Myth, Why It Is a Bigger Deal Than People Think
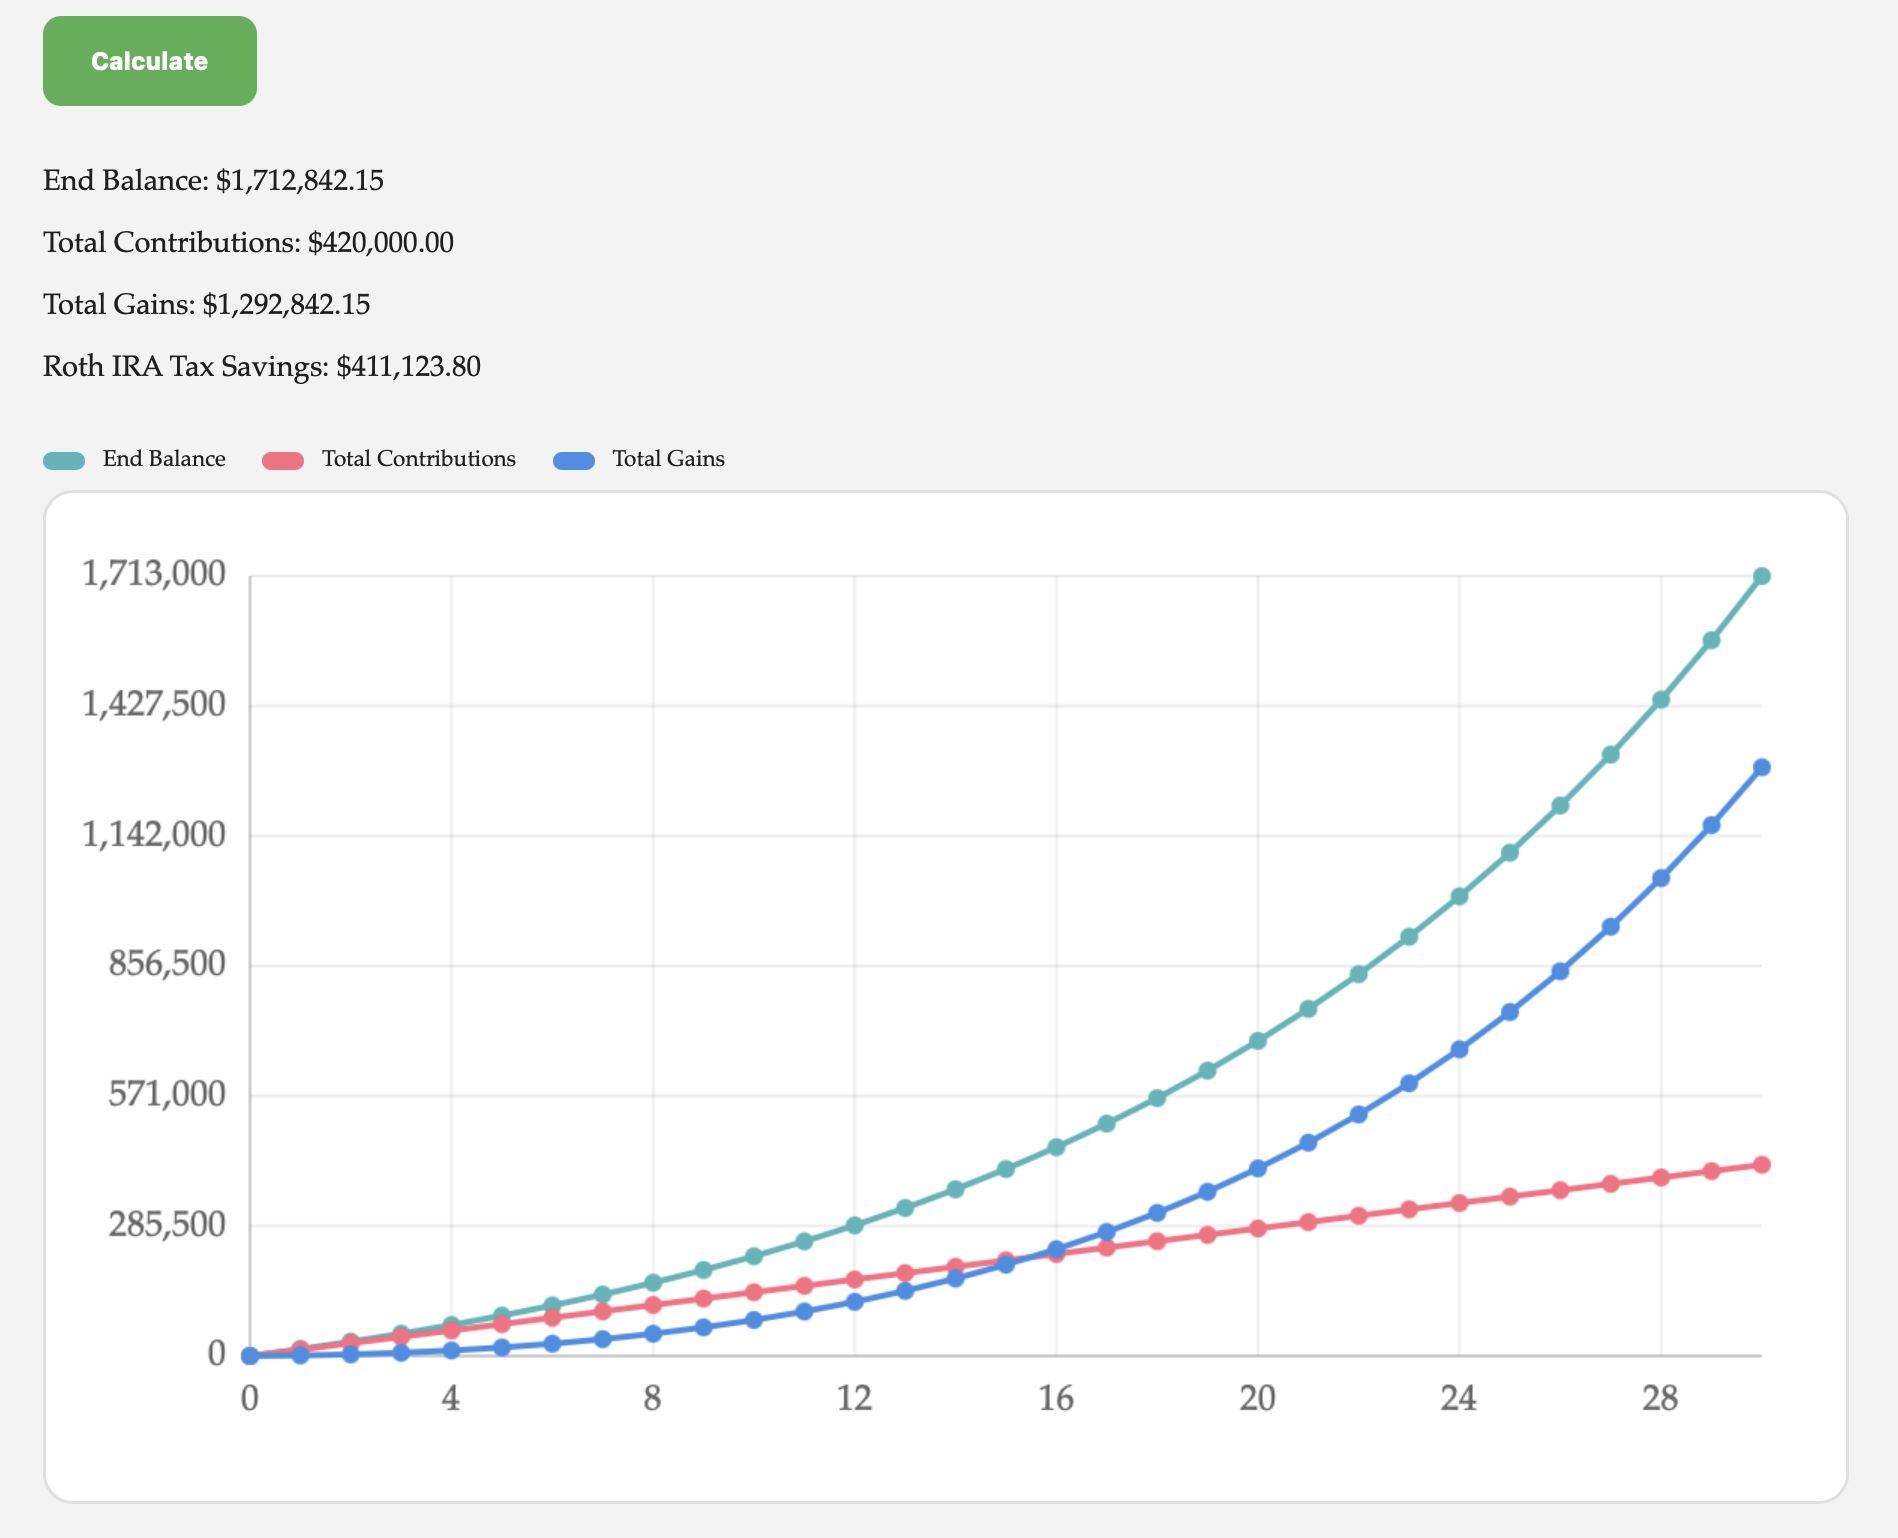
Many people look at the $7,000 annual Roth IRA limit and immediately dismiss it. Too small, not impactful, not worth the hassle. Big mistake! Let’s use a simple example. A husband and wife each contribute $7,000 a year, so $14,000 total, from age 30 to 60. That is 30 years of steady investing at an assumed 8 percent return. Total contributions come to $420,000. By age 60, that Roth balance grows to about $1.6 million. Roughly $1.16 million of that is pure growth, and it comes out tax free. If you live in a no state tax environment, you just avoided federal long term capital gains and the extra 3.8 percent surtax on investment income, already a meaningful number. Now layer in a high tax state. At an 8 percent state tax rate, that same $1.16 million of gains would have faced another large haircut (actually like $411K tax savings). The Roth just simply protects such a big chunk of your gain. The following are results from our Investment Return Calculator: And it does not stop there. Most people do not touch Roth money first. They let it keep compounding while spending from pre tax or taxable accounts. Let that same Roth grow another 10 years, untouched, at the same 8 percent. By age 70, it is worth roughly $3.9 million. Now you are looking at close to $3.3 million of gains that will never be taxed. In a zero state tax scenario, that already avoids a large federal tax bill. In an 8 percent state tax scenario, the difference becomes even more dramatic: a $1 million savings. This is where people underestimate the impact. The contribution feels small. The tax free compounding over decades is not. This is real money, not theoretical. High income earners often respond with another objection. Fine, but my income is too high to contribute to a Roth IRA anyway. Not really. This is where the backdoor Roth comes in. The process is simple in concept. You contribute to a traditional IRA using after tax dollars, since there is no income limit on contributions. Then you convert that contribution to a Roth IRA. If done correctly and promptly, there is little to no tax cost. The key rule is that you cannot have other pre tax IRA balances sitting around, including SEP or SIMPLE IRAs, or the conversion becomes partially taxable. Many people solve this by rolling old IRAs into a 401(k) first. Once set up, this becomes a repeatable annual process. So the real question is not whether the Roth is too small to matter. It is whether you want to keep paying taxes on millions of dollars of future growth, or quietly opt out while you still can.
-

Ultimate 2026 Retirement Playbook for 401(k)s & IRAs
Extremely use tips to maximizing 401(k) match, RMDs and IRA tactics
-

New Year Resolutions for Your Personal Finance
- Latest in Retirement Savings & Personal Finance
- New Year Resolutions for Your Personal Finance
- MyPlanIQ 2026 Market Outlook
-
2025 Crystal Ball Market Prediction Scorecard
- Latest in Retirement Savings & Personal Finance
- Stock Market Bubble & Retirement Savings
- Tools & Tips: Retirement Spending Calculator
- Market Overview
-

Personal Finance Year End Check List
- Latest in Retirement Savings & Personal Finance
- Personal Finance Year End Check List
- Tools & Tips: 12% Tax Bracket Is the Sweet Spot for Roth IRA Conversion
- Market Overview
-

How A Valuation Driven Bear Market Looks Like
- Latest in Retirement Savings & Personal Finance
- Stock Market Bubble & Retirement Savings
- Tools & Tips: Retirement Spending Calculator
- Market Overview
-

Retirement Plan Contribution Limits in 2026
Comprehensive retirement plans (401(k), 403(b, 457(b), Solo 401(k), SEP IRA, SIMPLE IRA, IRA, Roth IRA, TSP, HSA etc.) contribution limits for 2026
-

How Retirement Savings Can Quietly Reduce Your Student Loan Payments
Increasing Retirement Savings such as 401(k) can help reduce your monthly student repayment if you are on the federal IBR program. But
-

Super Businesses, Super Stocks
- Latest in Retirement Savings & Personal Finance
- Super Businesses, Super Stocks
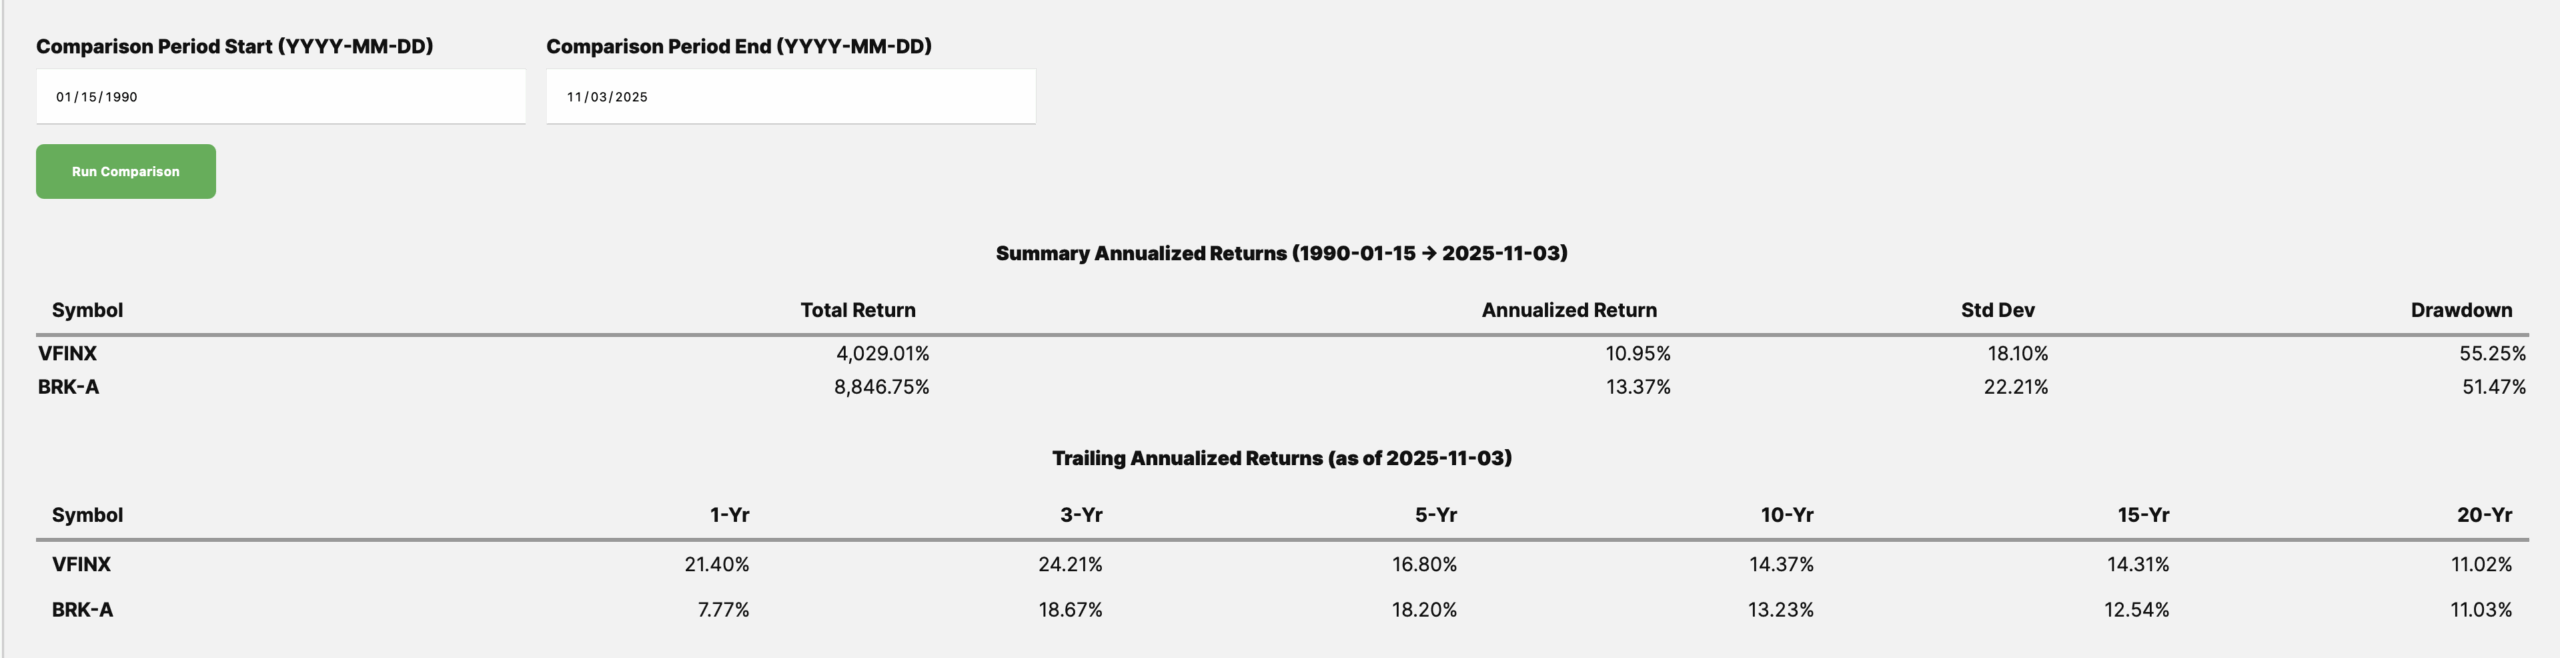
- Tools & Tips: Return Comparison Calculator
- Market Overview
-

2024 Millionaire Retirement Plans
- Latest in Retirement Savings & Personal Finance
- 2024 Millionaire Retirement Plans
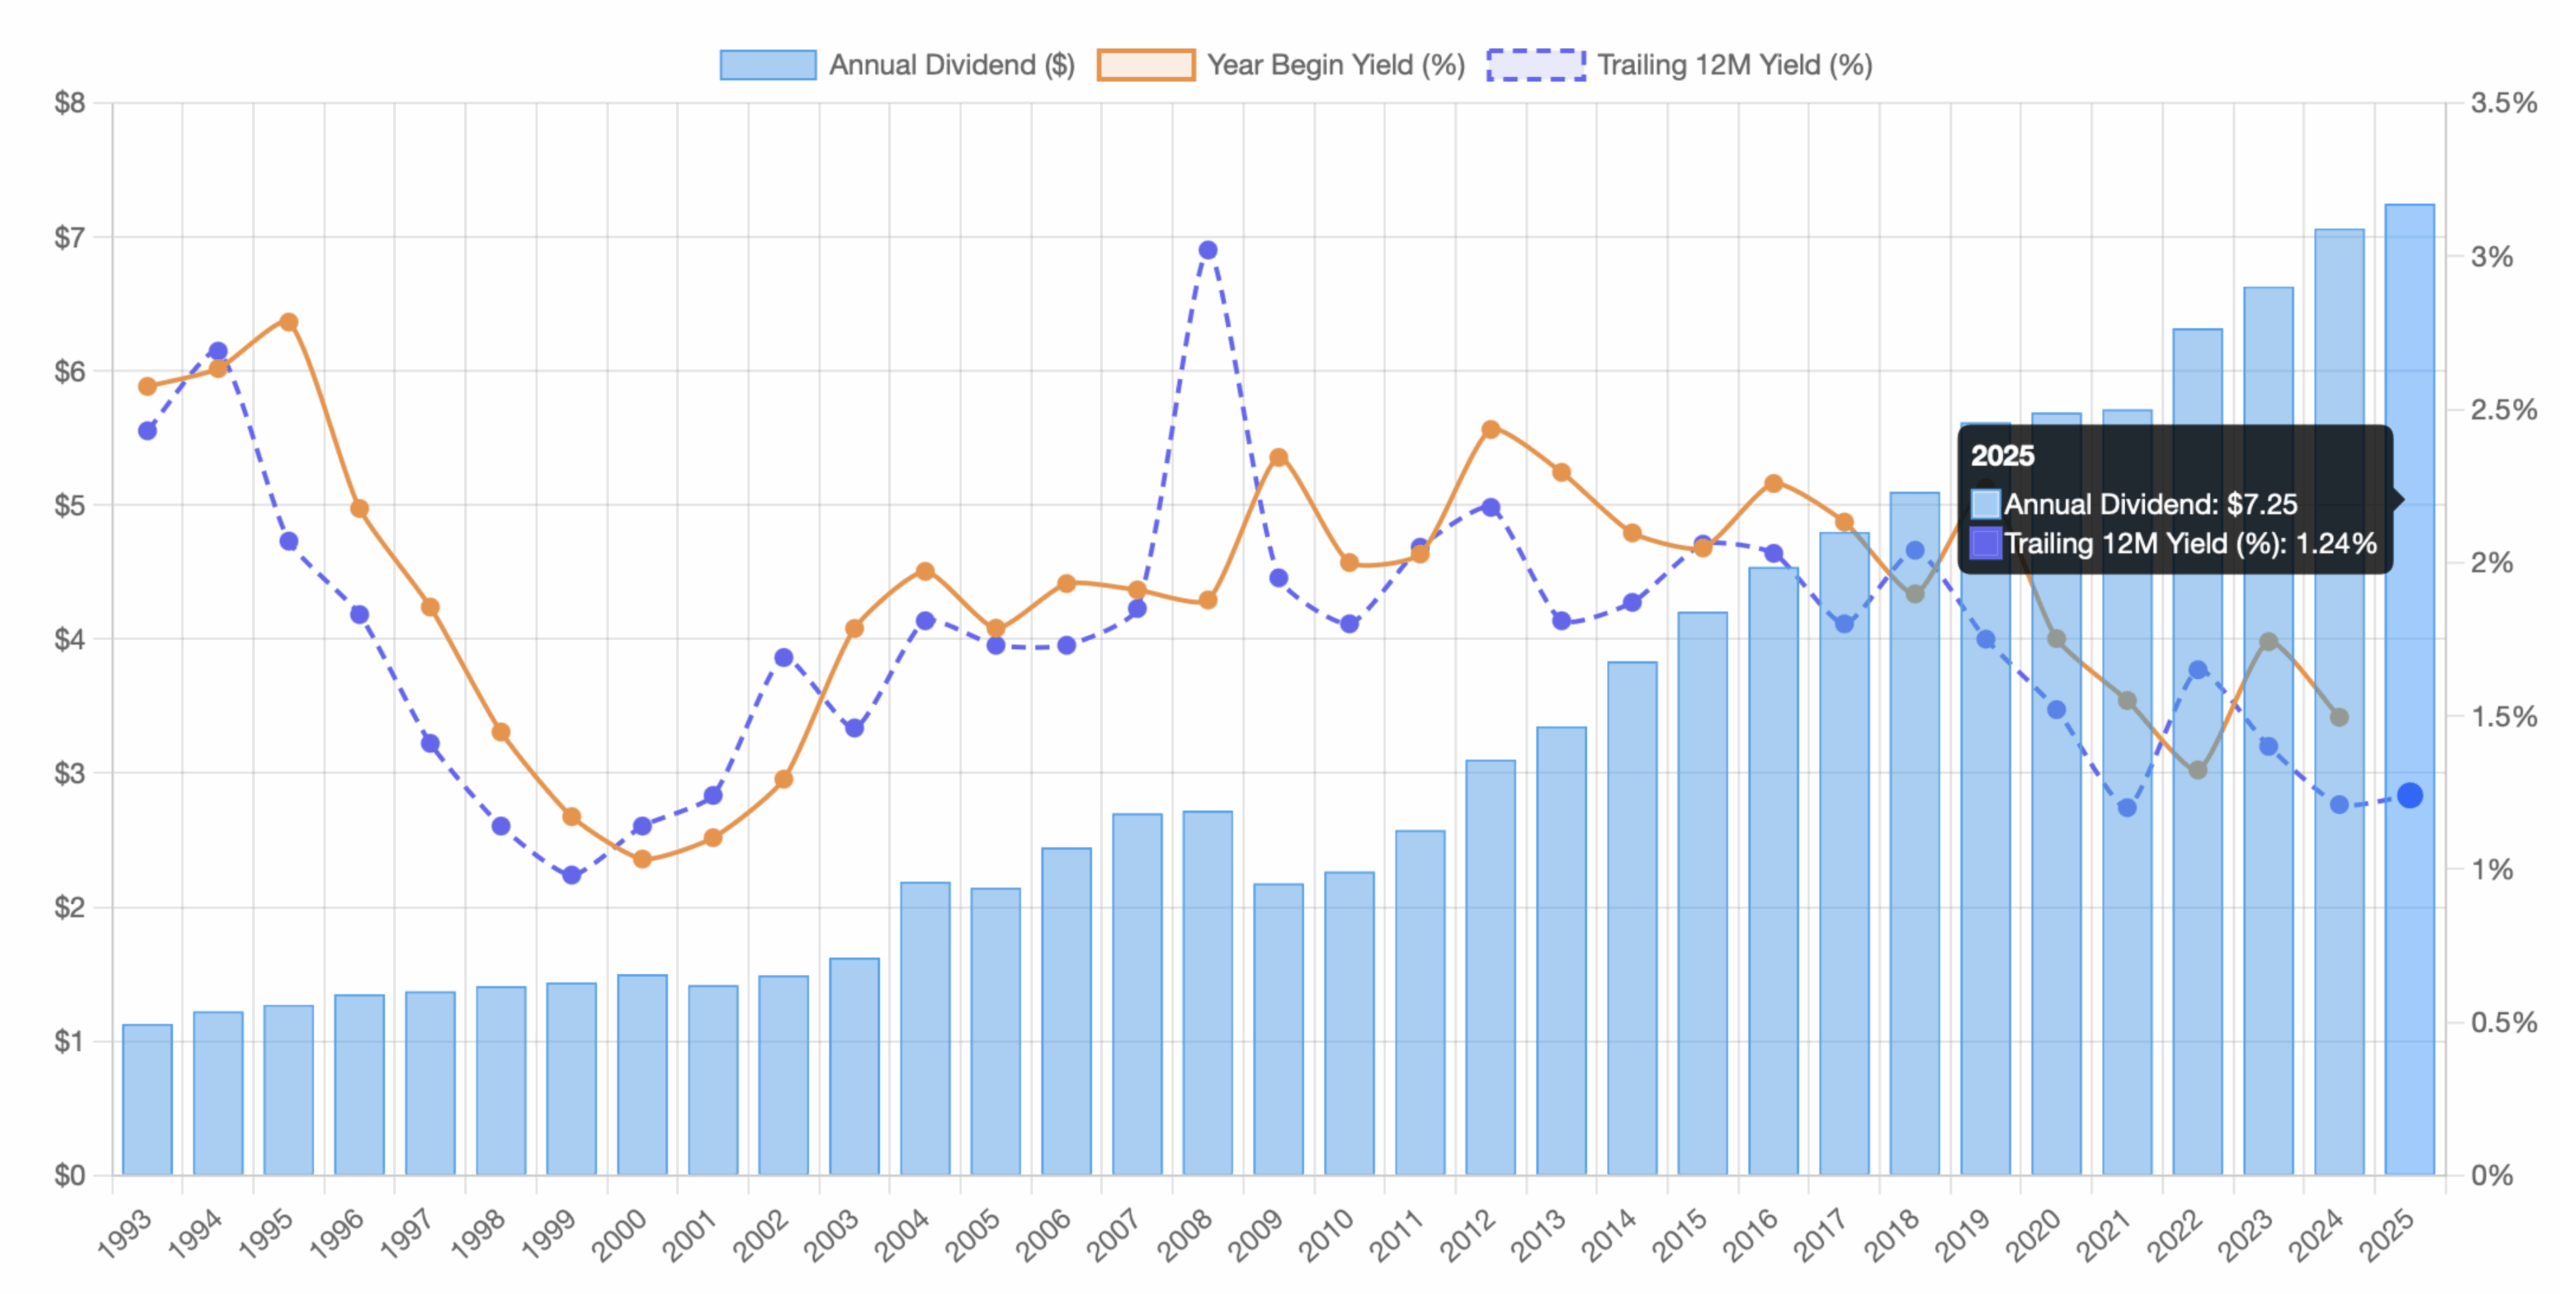
- Tools & Tips: Historical Stock Dividend Yield Chart
- Market Overview
-

Last Quarter Checklist for 2025
- Latest in Retirement Savings & Personal Finance: All the Glittering Gold, Highest Household Credit Card Debt, More PE Funds Than McDonald’s
- Last Quarter Checklist for 2025
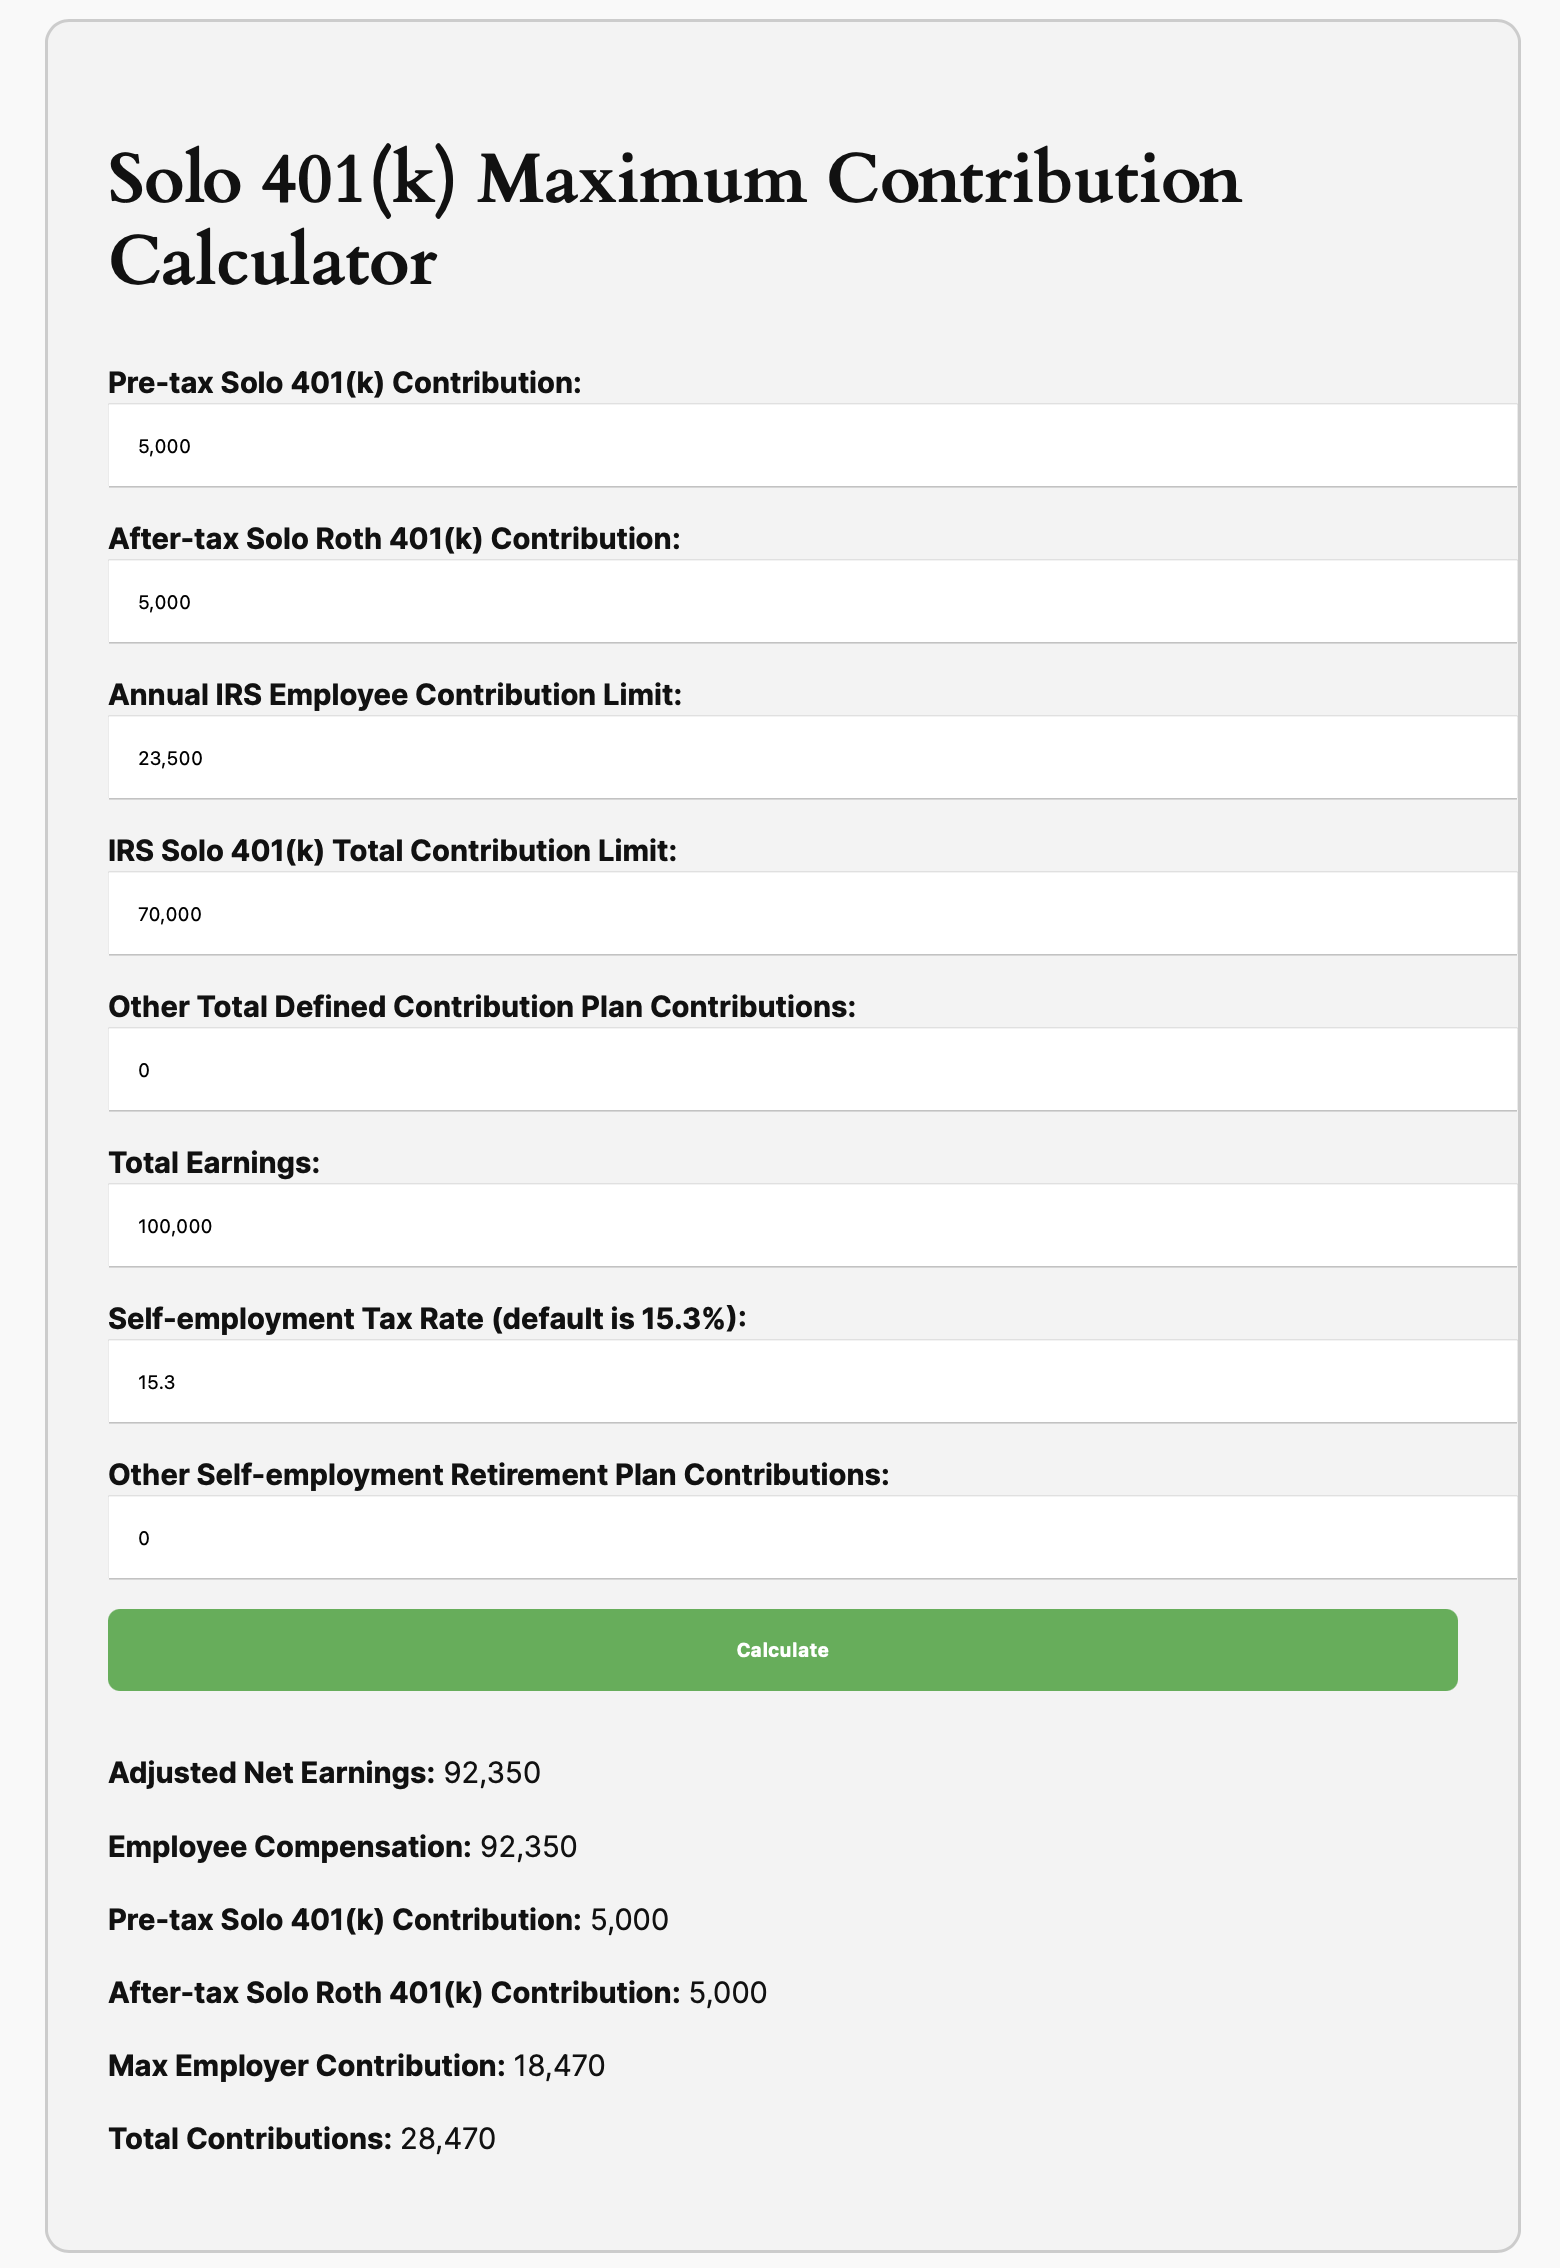
- Tools & Tips: Solo 401(k) Maximum Contribution Calculator
- Market Overview
-

HSA: One of The Biggest Tax Break You Shouldn’t Ignore
- Latest in Retirement Savings & Personal Finance: What Fed Rate Cut Means for You? Surge in Electricity Prices
- Health Savings Account (HSA): One of The Biggest Tax Break You Shouldn’t Ignore
- Tools & Tips: HSA Savings Calculator
- Market Overview
-
Best Strategy to Withdraw Funds in Retirement
When you retire, the order you pull funds from your accounts (whether taxable, traditional, or Roth) can make big difference.
-
Retirement Plan Contribution Limits in 2024
2024 Retirement Plan Contribution Limits 1. 401(k), 403(b), and 457(b) Plans Employee Contributions: Up to $23,000 (under age 50) Catch-up contribution: $7,500 (ages 50+) Total Combined Limit (Employee + Employer): $69,000 Roth Options: Available for 401(k), sometimes for 403(b) and 457(b) Plan Details: 401(k): Primarily for for-profit companies; includes Roth (after-tax) options. 403(b): For public schools and nonprofits; Roth-style options less common. 457(b): For state/local government and some tax-exempt organizations; Roth availability varies. 2. Solo 401(k) and SEP IRA Solo 401(k): For self-employed individuals/business owners without employees.
- Employee contributions: $23,000, plus $7,500 catch-up (ages 50+)
- Employer contributions: up to 25% of compensation
- Total combined limit: $69,000 or 25% of compensation, whichever is less
SEP IRA: Employer contributes up to 25% of compensation, up to $69,000. No catch-up contribution. 3. SIMPLE IRA
- Employee contribution: up to $16,500
- Catch-up contribution: $3,500 (50+)
- Employer must match dollar-for-dollar up to 3% of employee salary
- Immediate vesting
4. Traditional and Roth IRAs
- Annual contribution: $7,000
- Catch-up: additional $1,000 (50+)
Traditional IRA: Pre-tax contributions, taxable upon withdrawal Roth IRA: After-tax contributions, tax-free withdrawals 5. Thrift Savings Plan (TSP)
- Federal and uniformed services employees only
- Employee contributions: up to $23,000 (under age 50), plus catch-ups ($7,500 at 50+)
- Employer matches up to 5% of salary
- Total Combined Limit (Employee + Employer): $69,000
- Pre-tax (traditional) and Roth contributions allowed
6. Payroll Deduction IRA
- Annual limit: $7,000; catch-up of $1,000 (age 50+)
- Pre-tax or Roth contributions
- No employer matching
7. Health Savings Account (HSA)
- Individual coverage: $4,150
- Family coverage: $8,300
- Catch-up contribution: additional $1,000 for age 55+
- Must have a high-deductible health plan
- Tax-free growth; penalty-free medical withdrawals; penalty-free non-medical withdrawals after age 65 (taxable)
8. Self-Directed IRA (SDIRA)
- Contribution limits same as IRAs ($7,000 + $1,000 catch-up age 50+)
- Allows alternative investments (real estate, precious metals, crypto)
- Requires IRS-approved custodian
9. Nondeductible IRA
- Same limits as traditional IRAs ($7,000 + $1,000 catch-up age 50+)
- Contributions not tax-deductible; earnings taxable at withdrawal
10. Annuities and Pension Plans (Brief Overview)
- Annuities: Insurance-based retirement products, providing guaranteed income. High fees, limited liquidity.
- Pension Plans: Employer-funded defined-benefit plans providing guaranteed lifetime income. Limited investment control.
11. Flexible Spending Account (FSA) Limits for 2024
- The maximum employee contribution to a health care FSA for 2024 is $3,200.
- If the FSA plan allows for carryover, the maximum amount that can be carried over to 2025 is $640.
- For Dependent Care FSAs, the maximum remains $5,000 per household (single or married filing jointly) or $2,500 if married and filing separately.
12. Health Savings Account (HSA) Limits for 2024 Coverage Type 2024 Contribution Limit Catch-Up (Age 55+) Minimum Deductible Out-of-Pocket Max Self-only $4,150 +$1,000 $1,600 $8,050 Family $8,300 +$1,000 (per eligible spouse, each in own HSA) $3,200 $16,100
- Individuals age 55 or older can contribute an additional $1,000 as a catch-up contribution.
- HSA contributions can be made until the tax filing deadline (April 15, 2025, for tax year 2024).
- To be eligible for HSA contributions, you must be enrolled in a high-deductible health plan (HDHP) meeting the minimum deductible and out-of-pocket maximum requirements above.
-

Simple 401(k) Investment Guide
In this issue:
- Latest in Retirement Savings & Personal Finance: College Education Affordability Declined, Rising Debt Puts Your 401(k) Retirement Savings in a Pickle
- Simple 401(k) Investment Guide
- Tools & Tips: 401(k) Investment Assistant
- Market Overview
-
Income Growth, Historical 401(k) Contribution Limit Data
In this issue:
- Latest in Retirement Savings & Personal Finance: Interest Rates Rise Again, Rising Home Insurance Cost, …
- Historical Income Growth, 401(k) Contribution Limit Growth
- Tools & Tips: 401(k) Maximum Match Calculator — Marvell Semiconductor
- Market Overview
-
How Much Should I Save for Retirement By Age? A Realistic Reference
In this issue:
- Latest in Retirement Savings & Personal Finance: Medicare Rude Surprise, Scoop to Be a Millionaire
- How Much Should I Save for Retirement By Age? A Realistic Reference
- Tools & Tips: Retirement Savings by Age Calculator
- Market Overview
-

Realistic Reference Data on Retirement Savings by Age in 2025
A realistic accumulated savings figures by age in 2025 for various income level people.
-

Warren Buffett’s Phenomenal Run: The Oracle May Retire, But His Legacy Endures
In this issue:
- Latest in Retirement Savings & Personal Finance: Social Security Early Claims Surge, Student Loan Collection Resumed, …
- Warren Buffett’s Phenomenal Run: The Oracle May Retire, But His Legacy Endures
- Tools & Tips: Rolling Return Calculator
- Market Overview
-

One Fund Does It All
In this issue:
- Latest in Retirement Savings & Personal Finance: US Food & Engergy Inflation Charts, Empty Shelfs Coming? Part-time Contractors Rejoin on 401(k) Eligibility
- One Fund Does It All: Savings & Investing in 401(k) Might Not Be That Intimidating
- Tools & Tips: Retirement Spending Calculator
- Market Overview
-

The One-Fund 401(k) Portfolio: Simple Yet Does Its Job
One-fund portfolio, either a target-date fund or just a balance index fund, does a good job for retirement plan investors who have little experience or who don’t want to mess around.
-
Roth IRAs for Retirees
Roth IRAs can be very useful for retirees in terms of medicare premiums, estate planning and other benefits.
-

Lazy Portfolios Aren’t Lazy in Growing Wealth
In this issue:
- Latest in Retirement Savings & Personal Finance: Golden Rule and The Roth IRA Evangelist
- Lazy Portfolios Aren’t Lazy in Growing Wealth
- Tools & Tips: Investment Arithmetic
- Market Overview
-

IRAs as One of the Emergency Fund Sources
In this issue:
- Latest in Retirement Savings & Personal Finance: Back-and-forth Tariff Policies, Stock Market Swings, and Low Retirement Savings Rates
- IRAs as One of the Emergency Fund Sources
- The Gotcha in Maximum Solo 401(k) or SEP IRA Contribution Limits
- Market Overview
-
How to Borrow From an IRA?
There are several ways to take money out for short-term emergency purposes. This article explores some of those options.
-

Special Issue: Staying the Course Amid Market Turmoil
In this special issue:
- Latest in Retirement Savings & Personal Finance: Market Turmoil, Majority of Americans Invest in Stocks, …
- Staying the Course Amid Market Turmoil
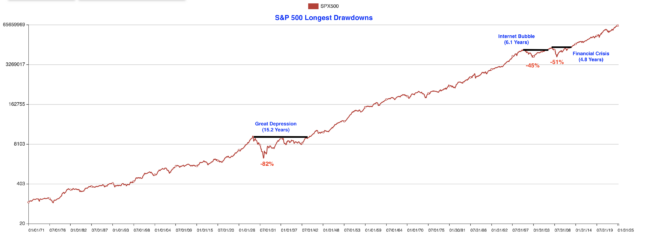
- Tools & Tips: Longest S&P 500 Losses (Drawdowns)
- Market Overview
-

The ABCs of Roth Conversions: Backdoor, Mega Backdoor, and More
In this issue:
- Latest in Retirement Savings & Personal Finance: Tariff Liberation Day, Beefing Up Emergency Savings, and Consumer Confidence at Its Lowest
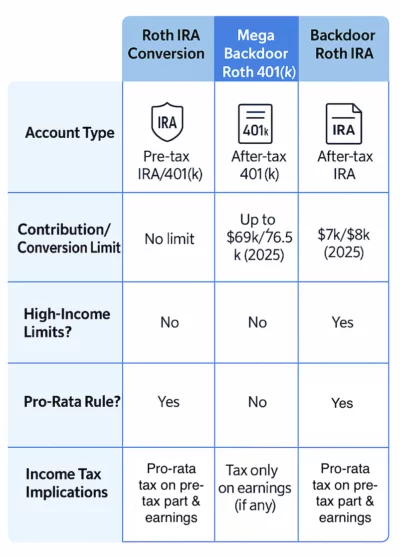
- The ABCs of Roth Conversions: Backdoor, Mega Backdoor, and More
- Tools & Tips: Social Security Income Calculation Infographic
- Market Overview